Think of knowing how to eat healthy versus actually choosing a salad over a burger. Knowing the nutritional facts rarely stops someone from reaching for the fries. In the world of personal finance, a remarkably similar disconnect exists between knowledge and action. Traditional economic models operate on the assumption that once a person learns the route to better financial wellness, they will automatically take the necessary steps to achieve it. However, just because we know saving money leaves us better off in the future, many of us still find it incredibly difficult to actually do it.
This behavioral gap severely undermines traditional community-based financial education programs. When educators simply hand out information on budgeting and debt repayment, individuals frequently fail to take a course of action to improve their financial well-being, even after they have learned exactly how to do so. A myriad of complex social and psychological factors constantly stand in the way of rational decision-making. To bridge this gap, financial educators are realizing that providing sheer information is no longer enough; they must actively target the psychological factors that hinder financial execution.
To provide educators with better tools, a team of researchers including Rebecca C. Smith, Cäzilia Loibl, Khurram Imam, and Lauren Jones explored the integration of behavioral economics into financial education. Published in the Journal of Extension, their article addresses how community professionals can utilize a fusion of behavioral science, psychology, and neuroscience to improve financial outcomes. Specifically, the researchers focused on the implementation of “nudges”—low-cost, replicable initiatives designed to remove everyday psychological barriers to saving and financial planning while preserving consumer choice.
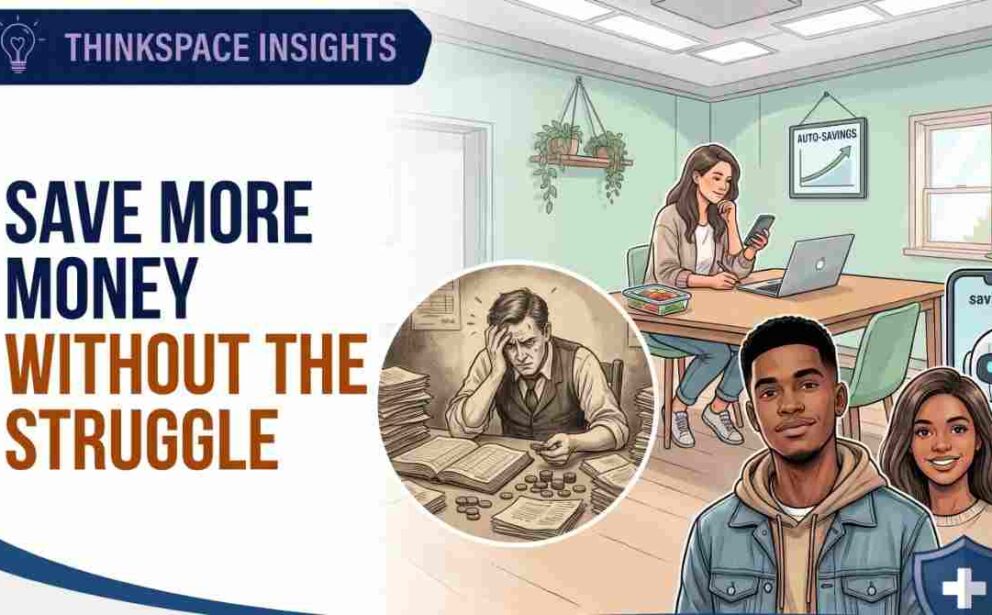
The research categorizes these interventions into two distinct psychological mechanisms based on established behavioral science. “System 1” nudges are effortless and automatic, guiding behavior without a person consciously noticing. Examples include setting up automated direct deposits into a savings account or funneling a future raise directly into a retirement account before the individual gets used to spending the extra money. Conversely, “System 2” nudges require deliberate decisions and are affected by how a choice is framed, such as offering information about how much other people save or sending goal-specific text reminders.
Implementing these psychological tools requires navigating human preferences carefully. While people generally prefer obvious System 2 interventions because they want to feel in control of important decisions, automatic System 1 nudges are often much more effective at permanently changing behavior. For practical application, the researchers recommend that financial professionals design simple nudges and integrate them into interactive programs. This includes utilizing tools like the “Bean Game” to force visual budgeting decisions, or encouraging clients to use modern banking apps that automatically round up purchases to transfer spare change into savings.
Ultimately, combining traditional financial education with behavioral nudges provides a highly effective strategy for improving community outcomes. By utilizing these quick-to-implement approaches, professionals can successfully tackle common behaviors like repaving debt, budgeting, and breaking poor spending habits. Moving forward, the study suggests that financial educators should partner directly with large employers to implement automatic savings programs tied to paychecks, ensuring that healthy financial behaviors become the effortless default rather than the exception.
ThinkSpace Insights
- The knowledge disconnect, as traditional economic models falsely assume that simply teaching people how to save will automatically lead to better financial behavior.
- Hacking human behavior, highlighting that behavioral economics fuses psychology and neuroscience to specifically target the psychological factors that hinder financial wellness.
- The power of the nudge, explaining that nudges are low-cost, replicable initiatives that preserve consumer choice while removing everyday barriers to financial planning.
- Automatic pilot, noting that System 1 nudges rely on effortless, automatic processes, such as setting up direct deposits or automated credit card payments.
- Framing the decision, revealing that System 2 nudges require deliberate decisions, such as warning consumers about the true cost of making only minimum credit card payments.
- Practical applications, concluding that financial educators should partner with employers and utilize automated banking apps to seamlessly integrate these interventions into daily life.
Access Full Article
https://www.researchgate.net/publication/371317455_Improving_Financial_Behaviors_Through_Nudges